

Before You Build Your 2027 Investment Thesis, Look at What Sport Is Becoming
3 Min Read
Before You Build Your 2027 Investment Thesis, Look at What Sport Is Becoming
Mature assets are compounding, new markets are being created, and the economics around every fan are expanding.
The world’s 50 most valuable sports teams are now worth approximately $353 billion combined, more than double their value only four years ago. (Forbes)
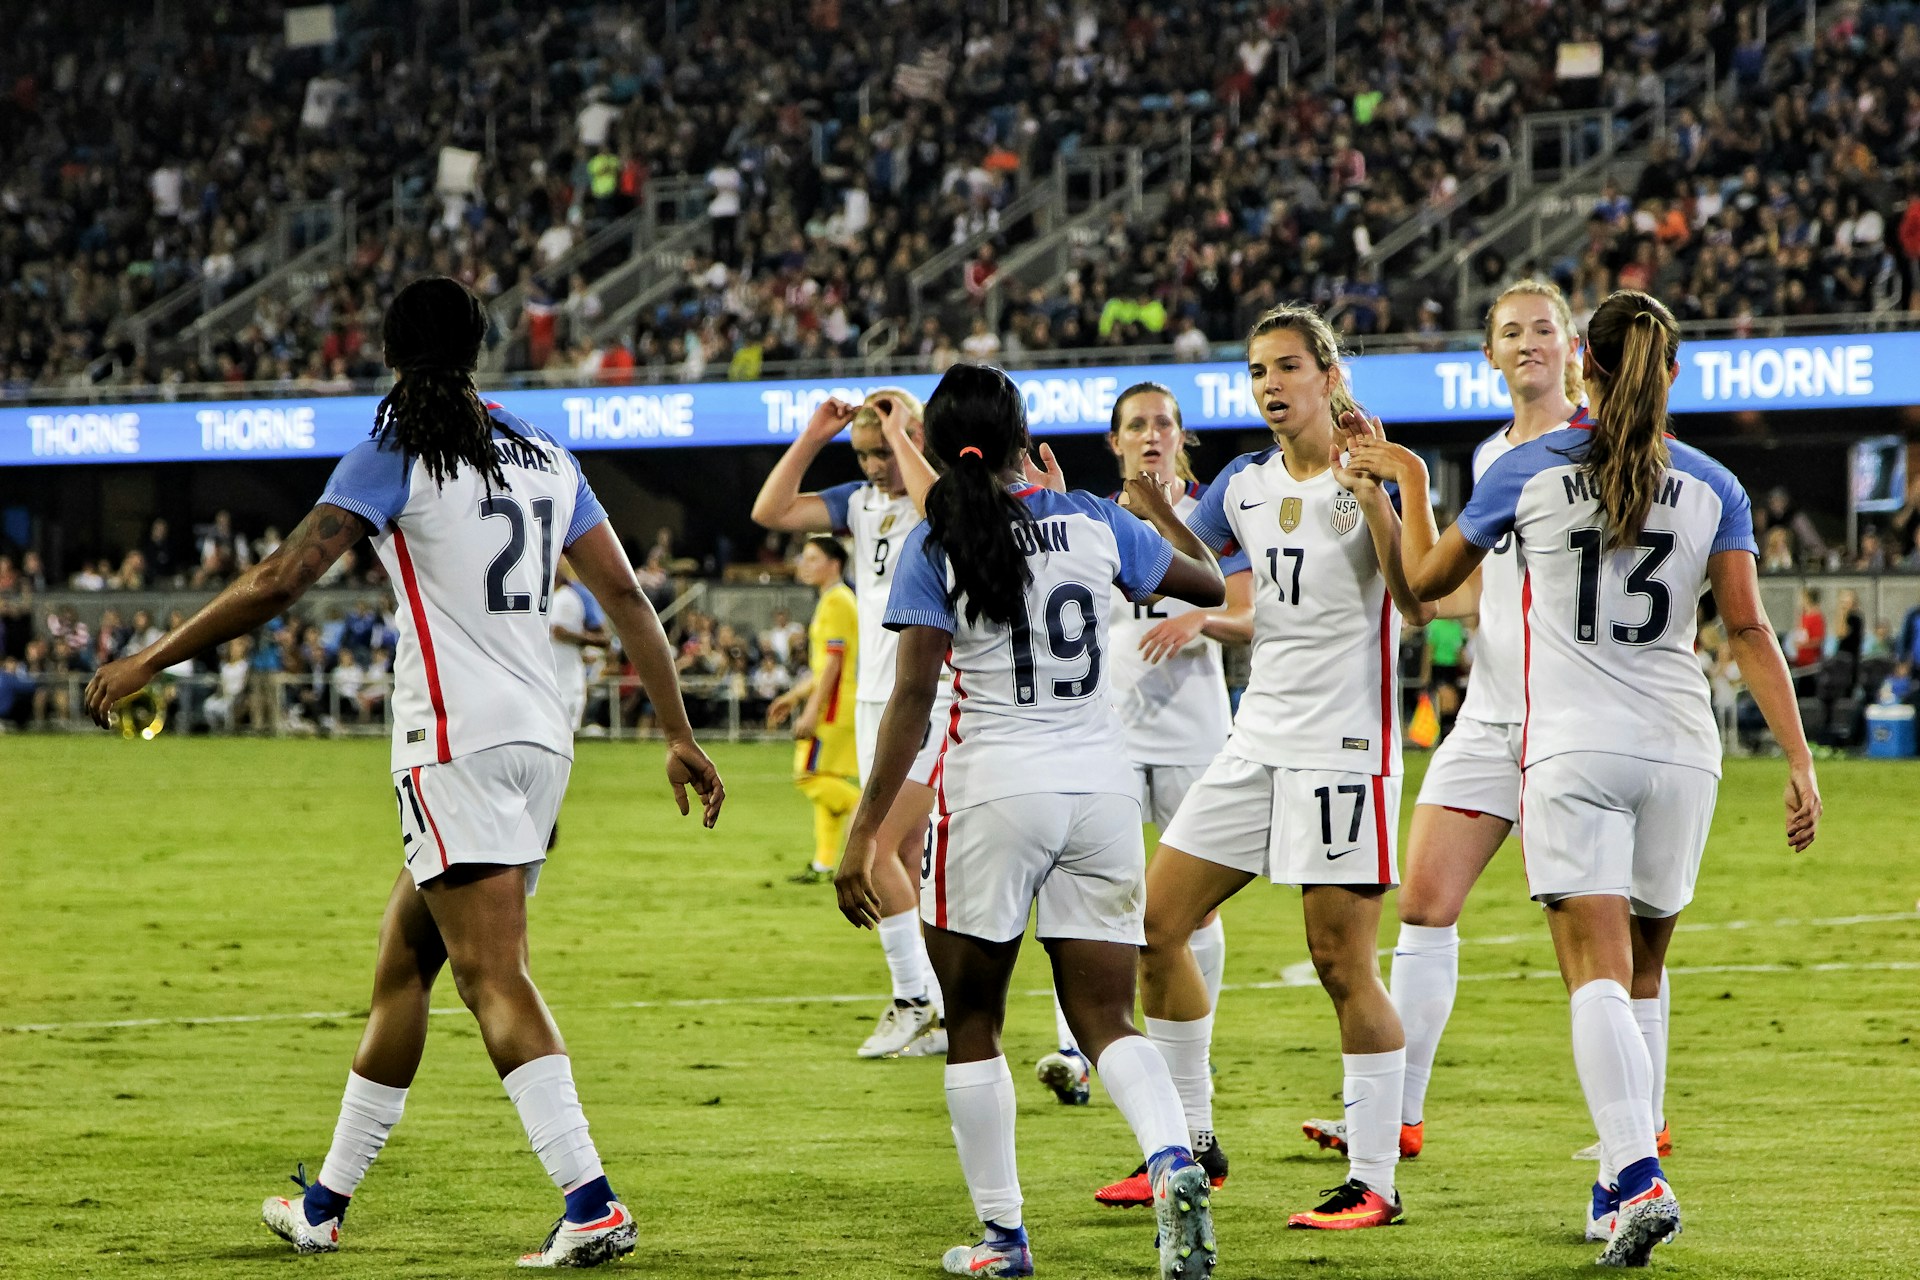
Elite women’s sports revenue is expected to reach $3 billion in 2026, up roughly 340% from 2022. (Deloitte)
US pickleball participation grew from 4.2 million people in 2020 to 24.3 million in 2025. (Sports & Fitness Industry Association)
NFL related videos generated more than 20 billion YouTube views in 2025, with over 30% happening outside the season. (blog.youtube)
These are not four separate trends.
They point to something more interesting:
A mature global industry is appreciating while simultaneously creating entirely new markets inside itself.
For investors planning 2027 and 2028, the question is no longer whether sport is growing.
It is:
Where inside the sports economy are the best economics beginning to form?
I would put three areas on the investment committee agenda.
1. Old assets are still compounding
Most industries eventually see their biggest assets mature.
Sport behaves differently.
Some of its most valuable properties are decades, even more than a century, old, yet their scarcity and commercial value continue to rise.
The top 50 teams more than doubled their combined value in roughly four years. (Forbes)
But the more interesting investment question is not:
Should we own the team?
It is:
Which companies can monetize appreciating sports assets without having to own them?
The property brings scarcity, identity and audience.
An infrastructure company can potentially bring scalability.
Payments. Data. Commerce. Hospitality. Media. Fan engagement. International distribution.
The opportunity is to find businesses whose economics improve as increasingly valuable sports properties look for more ways to monetize the same audience.
But keep the distinction clear:
Asset appreciation does not automatically create good supplier economics.
Margins, retention, customer concentration and pricing power still decide whether the company is investable.
2. Sport keeps creating new markets inside itself
This is where sport becomes unusual.
Most mature industries consolidate.
Sport keeps producing new categories.
Women’s elite sports revenue is projected to be roughly 4.4 times its 2022 level by 2026. (Deloitte)
US pickleball participation increased almost sixfold in five years. (Sports & Fitness Industry Association)
Every new category creates a new commercial stack.
Facilities.
Payments.
Membership.
Media.
Data.
Commerce.
Technology.
Sponsorship.
The investor question should therefore move beyond:
Which league wins?
Ask:
Who becomes essential infrastructure for every winner?
Think less about predicting one champion and more about identifying the businesses that can serve an entire category.
The analogy may be closer to Stripe, AWS or Shopify than to another sports property.
The most interesting company may be the one whose product can travel across football, women’s sports, creator led competitions and emerging sports without rebuilding itself every time.
That is where TAM can expand dramatically.
3. One fan can now support far more economic activity
This may be the least understood shift.
The same sports fan can now be a viewer, subscriber, YouTube user, podcast listener, bettor, gamer, traveler, merchandise buyer, hospitality customer and creator follower.
And much of that activity continues when no game is being played.
More than 30% of NFL related YouTube viewing in 2025 happened outside the season. (blog.youtube)
Sports documentary streaming consumption grew from approximately 4.7 billion minutes in 2021 to 16.9 billion in 2024. (Nielsen)
At HYPE SPORTS, we tried to quantify this broader expansion.
Our preliminary estimate suggests that the economic surface surrounding an engaged sports fan may have expanded roughly 2.7 times in five years.
This is a proprietary estimate, not an industry reported statistic.
The important point is the direction:
The fan did not become 2.7 times more passionate. The number of businesses capable of monetizing that passion expanded dramatically.
So ask:
Which companies participate in multiple revenue pools around the same fan?
A business that benefits whenever a fan watches, buys, travels, subscribes or renews can have very different economics from one dependent on a single transaction.
That is where recurring revenue and operating leverage become interesting.
Before your next investment committee, do five things
1. Build a 20 company sports economy watchlist.
Look beyond teams and leagues. Include infrastructure, data, commerce, fan engagement and emerging properties.
2. Pick three categories that barely existed on your radar five years ago.
Women’s sports. Creator led properties. New participation sports. Athlete media. Betting infrastructure.
3. Ask every management team one question:
If your sports category grows 3x, does your revenue grow with it automatically?
4. Look for cross category scalability.
Can the same product serve multiple sports and properties without significant reinvention?
5. Follow the economics, not the excitement.
Retention. Gross margin. Pricing power. Customer concentration. Repeatability.
Final Thoughts
Sport may provide the tailwind.
The company still has to provide the business model.
Established assets are appreciating.
New markets are forming.
And the economic surface around the fan is expanding.
The investment case is not simply that sport is growing.
It is that value is compounding at several layers at once.
Where in the sports stack are the best economics forming before everybody else sees them?

Comments